For physicians
Buying a home in San Diego as a doctor
Residents, fellows, new attendings and established doctors. Here's how the loans, the timeline and the trade-offs actually work.
Physician vs conventional vs VA loans
Physician loan
- Down payment
- 0–10%, varies by lender
- Mortgage insurance
- Usually none
- Student loans
- Often more flexible
- Qualify before your start date
- Often, on a signed contract
- Who qualifies
- MD and DO; some lenders add dentists, NPs, PAs and others
- Interest rate
- Can be higher than conventional
Conventional
- Down payment
- 3–20%
- Mortgage insurance
- PMI under 20% down
- Student loans
- Standard rules
- Qualify before your start date
- Sometimes, with limits
- Who qualifies
- Anyone who qualifies
- Interest rate
- Market rate
VA loan
- Down payment
- 0% for eligible borrowers
- Mortgage insurance
- No PMI; one-time funding fee unless exempt
- Student loans
- Standard VA rules
- Qualify before your start date
- Varies by lender
- Who qualifies
- Veterans, service members, some spouses
- Interest rate
- Often competitive
Typical features. Every lender sets its own rules.
From signed contract to keys
-
Sign your employment contract
This is the document most physician lenders will use to qualify you.
-
Book a call with me
We set your budget, target areas near your hospital and a target move date.
-
Talk to two or three physician lenders
Compare down payment, rate type, student loan treatment and closing window.
-
Get pre-approved
You need this letter before writing a serious offer.
-
Tour homes
In person or by live video if you're still finishing training somewhere else.
-
Make an offer
We write terms around your start date, not just the price.
-
Escrow, inspections and appraisal
Usually the first two weeks after your offer is accepted.
-
Close and get your keys
Before or after your start date, depending on your lender's rules.
Where doctors buy in San Diego
Five areas I'm asked about most, and the hospitals near each one.
-
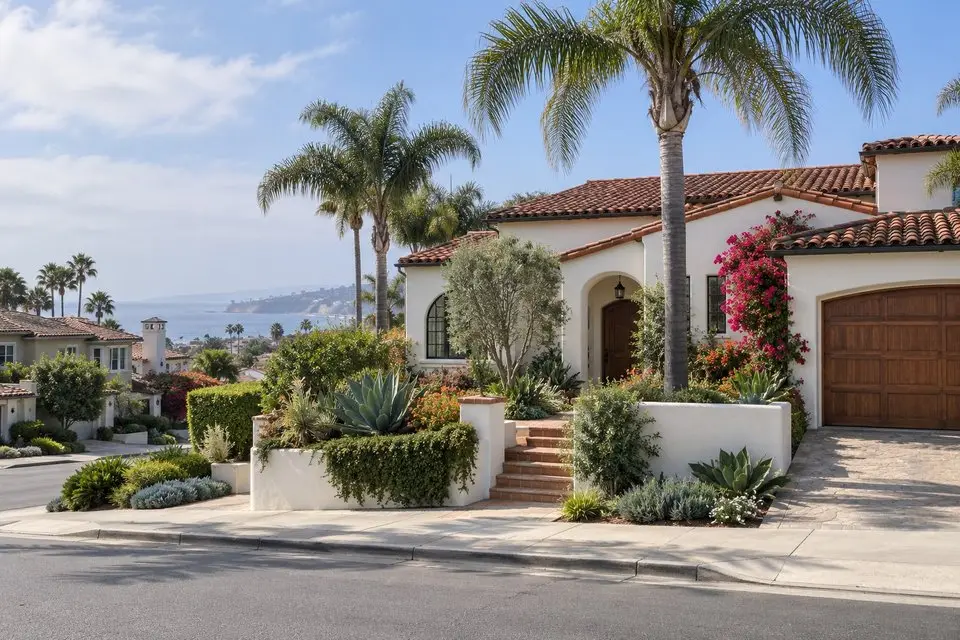
La Jolla
Coastal and quiet, near UC San Diego Health in La Jolla and Scripps Memorial La Jolla.
-
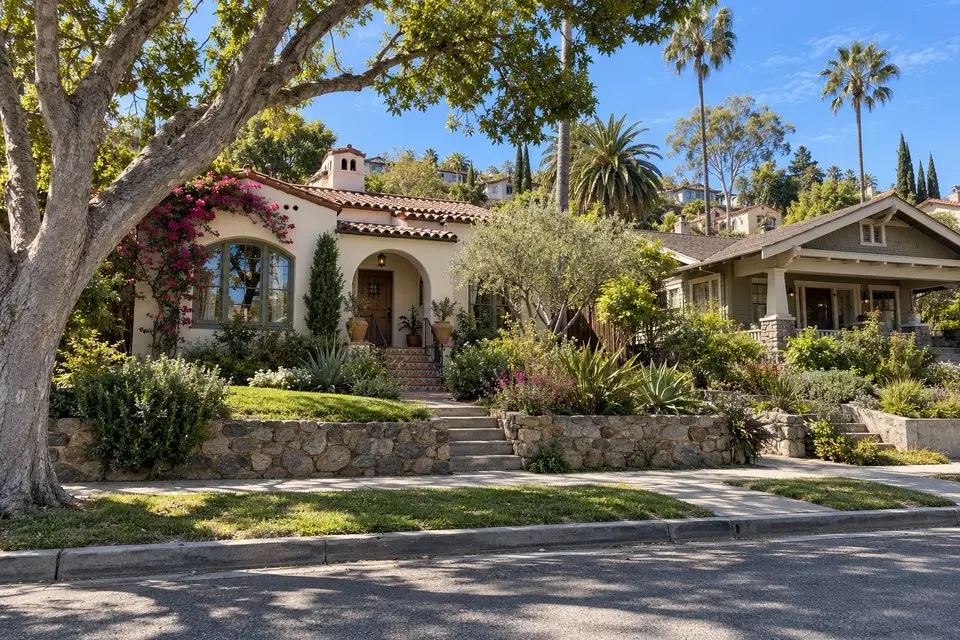
Mission Hills
Older homes on walkable streets, minutes from the Hillcrest hospitals and downtown.
-
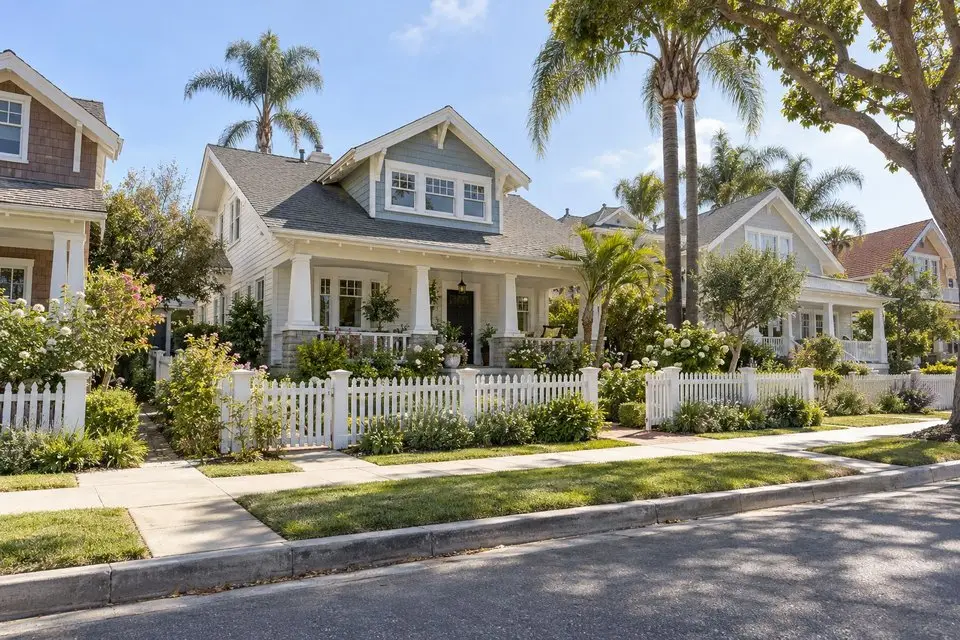
Coronado
Island living with Sharp Coronado Hospital in town and the bridge to downtown San Diego.
-
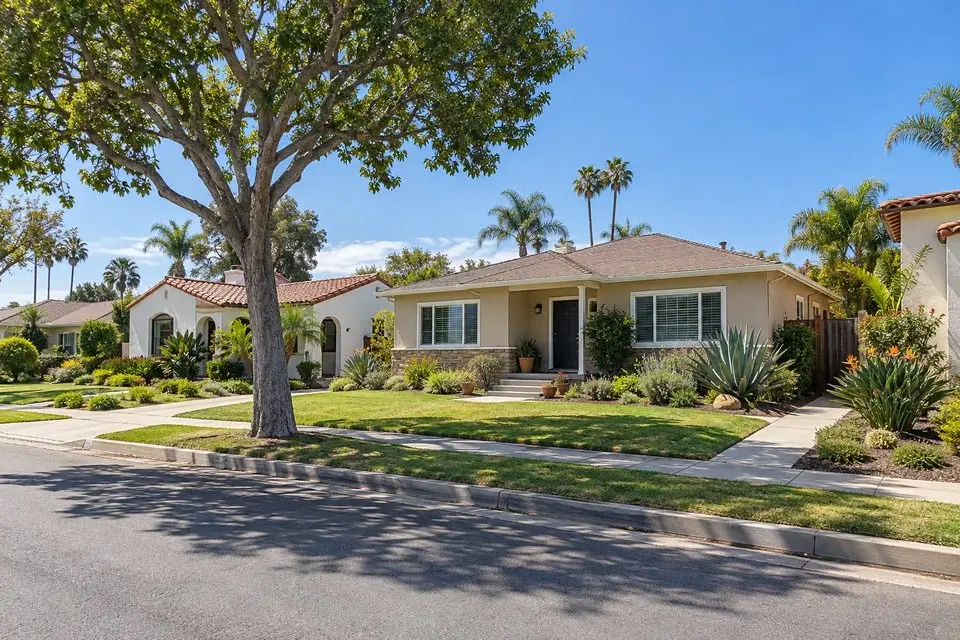
Chula Vista
More space for the money, near Sharp Chula Vista and Scripps Mercy Chula Vista.
-
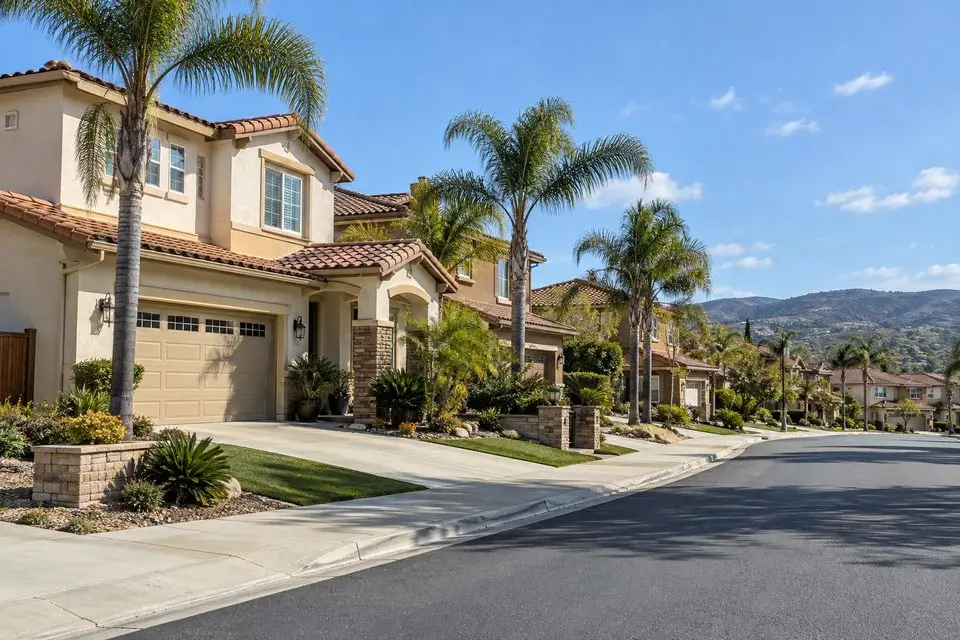
Eastlake
Newer planned neighborhoods in Chula Vista, with parks, trails and newer homes.
Representative photos.
The catches
- Rates can be higher than a conventional loan. Compare both.
- Low down payment means less equity if prices drop.
- Usually for a primary residence only, not rentals or second homes.
- Maximum loan amounts vary a lot between lenders.
- Adjustable-rate options are common. Read when and how the rate can change.
- Closing before your start date is often limited to a set window.
Questions to ask every lender
- Will you qualify me on my contract before I start? How far ahead can I close?
- How do you count my student loans?
- What's the most you'll lend at 0%, 5% and 10% down?
- Is there any mortgage insurance?
- Is the rate fixed or adjustable? For how long?
- Does my specialty or license type qualify (DO, DDS, NP, PA)?
- What are your total closing costs on a sample loan?
General information only. This is not a loan offer, tax advice or legal advice. Loan programs, rates and eligibility vary by lender and borrower. Verify terms with a licensed lender. Consult a licensed attorney or CPA for legal and tax questions.
Want this as a checklist you can keep?
The playbook has all of this plus worksheets for comparing lenders.